

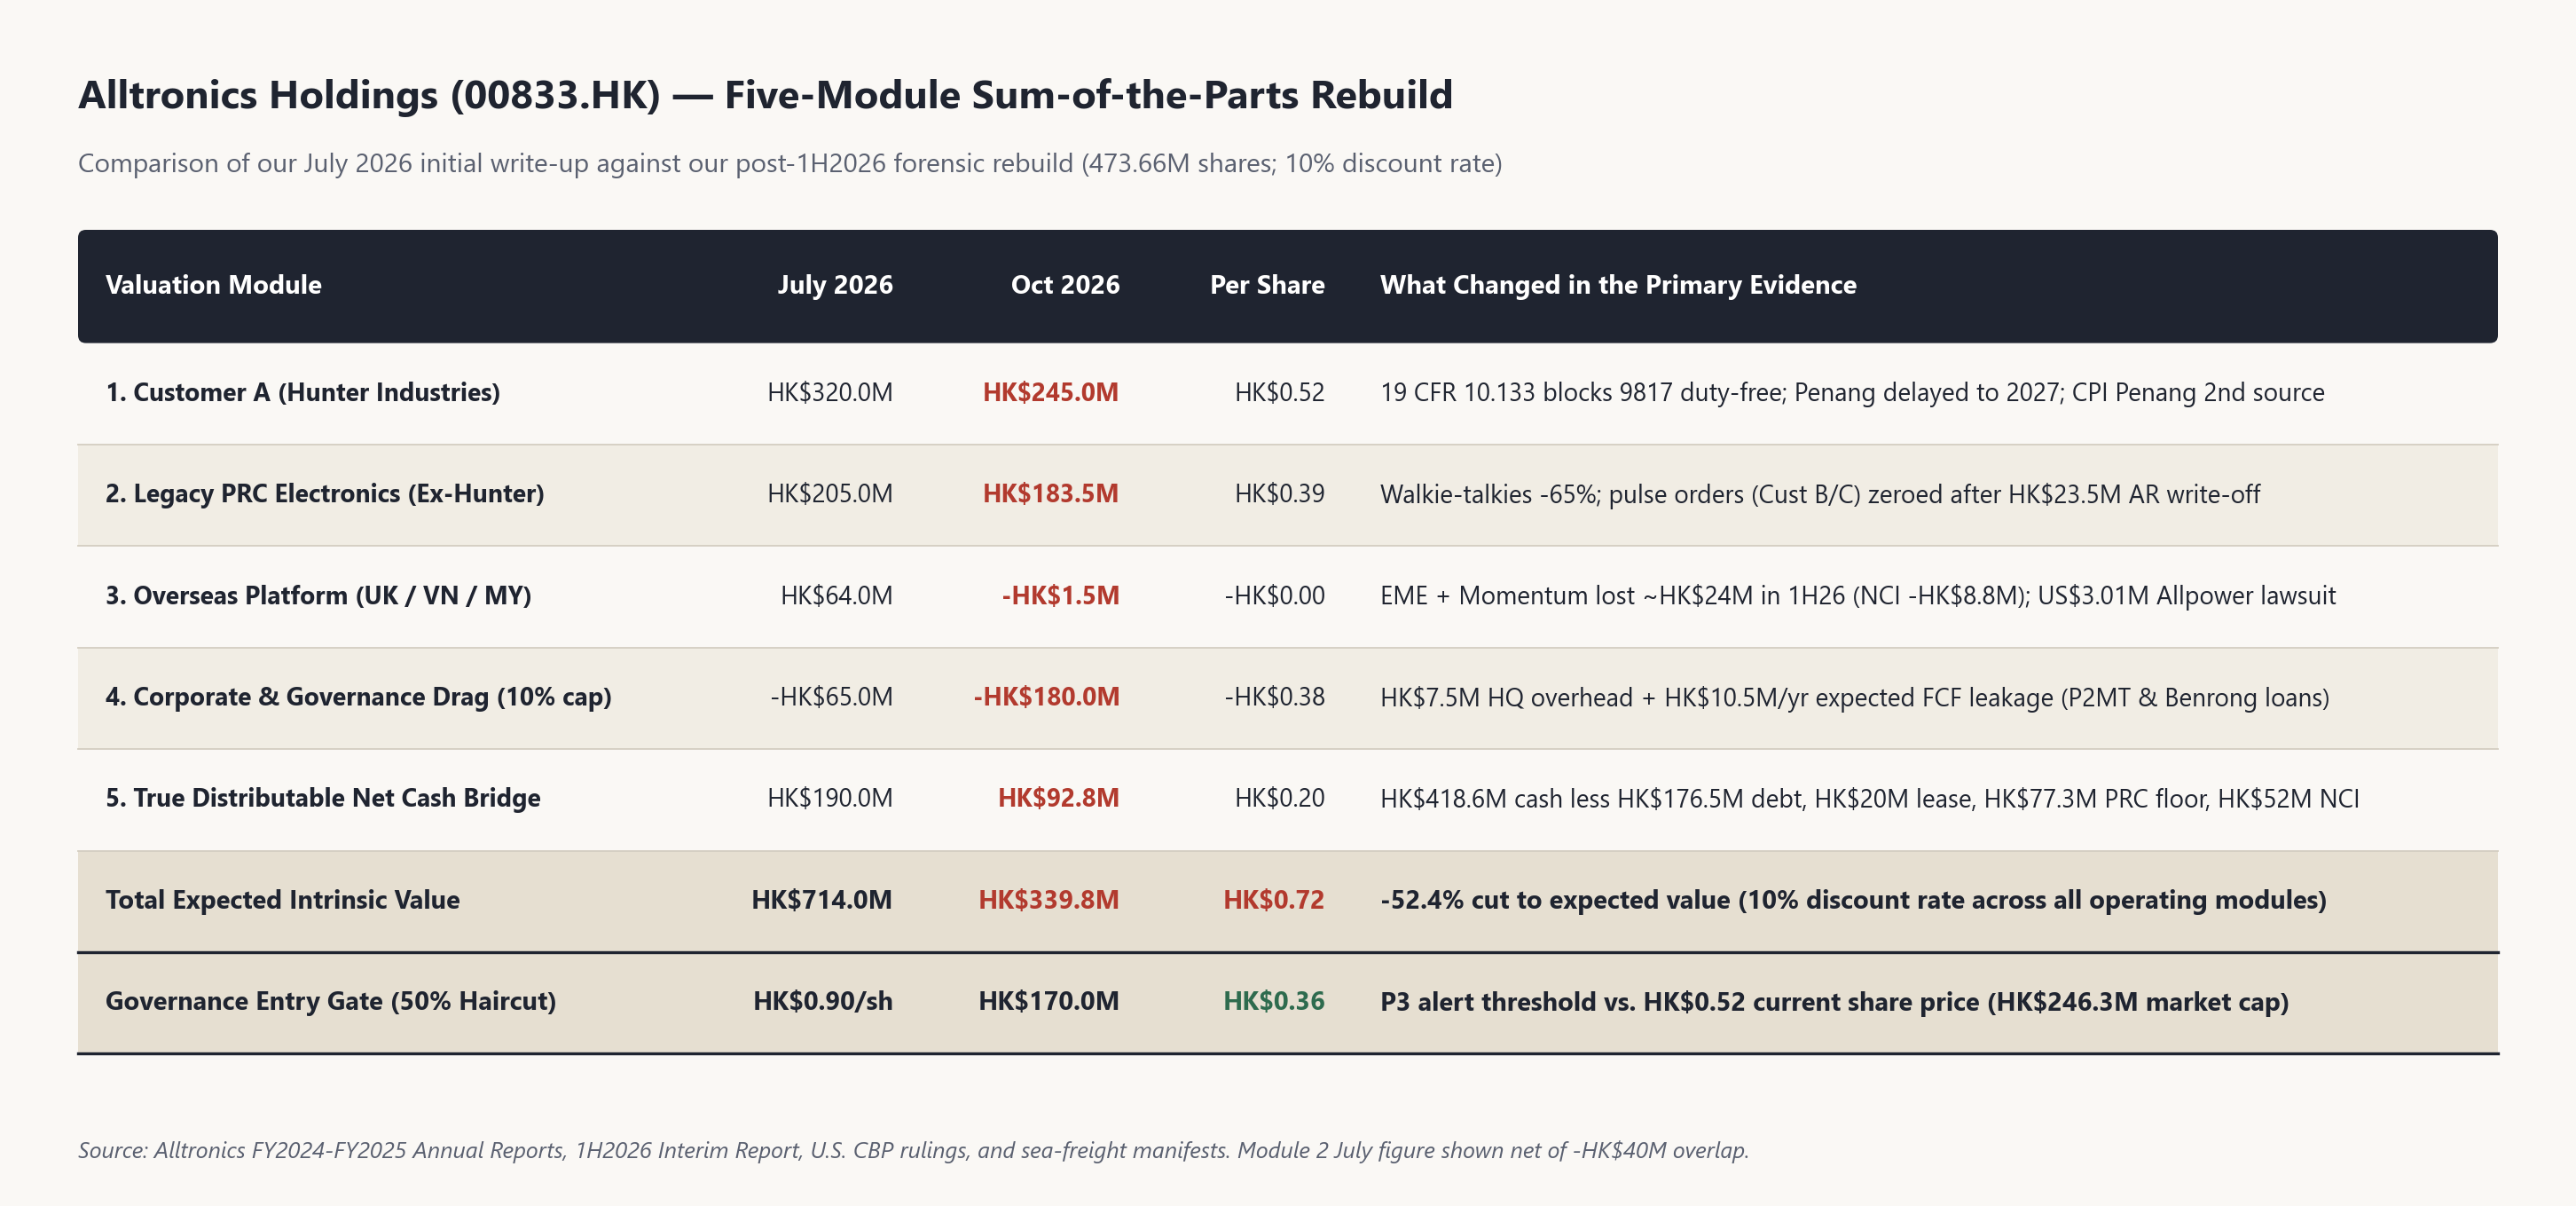
We cut our fair value estimate for Alltronics Holdings (00833.HK) to HK$0.72 per share (HK$340 million) from HK$1.51 per share (HK$714 million) in our July 2026 write-up. We overestimated margins, the speed of the Penang ramp, and management’s willingness to stop non-core lending. In the 1H2026 interim report released in late August, gross margin fell 500 basis points to 14.9%, reducing profit attributable to shareholders by 77.6% to HK$7.2 million despite 1.8% revenue growth to HK$624.5 million. Operating cash flow was negative HK$3.5 million, and the interim dividend was cut from 2.0 HK cents to 1.0 HK cent.
1. Customer A, U.S. Customs Actual-Use Rules, and Penang Capacity
Alltronics discloses that Customer A generated HK$455.8 million of revenue in FY2024, HK$546.6 million in FY2025 (45.6% of group revenue), and HK$323.2 million in 1H2026 (51.8% of group revenue). Shipping records suggest Hunter Industries in San Marcos, California is Customer A (462 matched U.S. sea-freight shipments across 14 irrigation controller product lines from Alltronics’s Shenzhen subsidiaries, Allcomm Electronic and Southchina Engineering); the company does not identify the customer in its filings.
Within southern China, Alltronics produces these controllers across three facilities: wholly-owned Yichun winds transformers and solenoid coils, 51%-owned Shenzhen Southchina molds outdoor plastic enclosures (generating over HK$400 million of intra-group transfers in FY2025), and wholly-owned Shenzhen Allcomm performs final assembly and testing. This vertical integration supported historical division gross margins near 21% and operating margins of 12% to 13%.
Our July valuation of HK$320.0 million for the Customer A business assumed that tariff pressure on Chinese shipments would be offset by U.S. agricultural tariff relief (HTS 9817.00.5000) and a fast transfer of U.S.-bound assembly to Winner Sky, the Penang, Malaysia subsidiary acquired in November 2025 for HK$9.15 million. Penang will not enter mass production until 2027, and we no longer assume broad agricultural duty relief.
While the U.S. Supreme Court invalidated IEEPA tariffs on February 20, 2026, the 25% Section 301 tariff on Chinese electronics remains in force. Duty-free entry under HTS 9817.00.5000 waives both standard MFN duty (1.3% to 2.7%) and the 25% Section 301 duty, but it is governed by the actual-use requirements of 19 CFR § 10.131–10.139. The importer must declare agricultural intent at entry, the equipment must be used in an agricultural or horticultural pursuit, and the importer must file end-user proof of actual farm use within three years under 19 CFR § 10.138. In binding rulings on irrigation equipment (NY N318224, HQ H264768, HQ 964998, and HQ H024976), U.S. Customs and Border Protection has held that residential lawn watering, commercial landscaping, and golf course turf maintenance do not qualify as agricultural pursuits. Because most of Hunter’s residential and commercial products are sold through wholesale distributors (SiteOne, Ewing) to landscaping contractors rather than directly to farms, collecting end-user farm certificates across multi-tiered distribution is impractical for residential and commercial turf lines.
The 1H2026 interim report (page 38) puts Winner Sky mass production in 2027. Per the FY2025 annual report (page 6), Winner Sky operates four SMT lines and eight assembly lines, with no plastic injection molding or transformer winding equipment disclosed. Under U.S. Customs country-of-origin standards (HQ H301619), shipping Chinese-made transformers and molded housings to Malaysia for final assembly carries origin-determination risk unless substantial transformation occurs locally.
Shipping records also identify CPI (Penang) Sdn. Bhd., an established Malaysian electronics manufacturer operating 36 plastic injection molding machines and 11 SMT lines, as an existing supplier to Hunter Industries (116 sea-freight shipments of controller decoders, ICC modules, and PCB sub-assemblies to Hunter facilities in California and Mexico, including 22 over the past 12 months).
Alltronics retains a deep mold library in Shenzhen and continues to supply Hunter’s non-U.S. sales (roughly 45% to 50% of Hunter’s volume). We value the Customer A business at HK$245.0 million (HK$0.52 per share), down HK$75.0 million from July, reflecting lower assumed steady-state NOPAT of HK$24.0 million (versus HK$32.0 million previously) as China shipments share tariff costs and CPI Penang competes for Malaysian volume.
2. Subsidiary Structure, Legacy PRC Electronics, and Receivable Write-Offs
Alltronics owns only 51% of Shenzhen Southchina Engineering, which is co-founded and managed by General Manager Yeung Kin San and Finance Director Leung Hon Kwong (who hold the remaining 49% equity). While wholly-owned Shenzhen Allcomm assembles finished controllers for Hunter, Southchina supplies internal plastic housings to Allcomm and ships water timers externally to Orbit Irrigation (a unit of Husqvarna Group), industrial switches to Grayhill, and battery testers to Midtronics.
Per Note 1 (page 108) of the FY2025 annual report, Southchina’s standalone revenue (including intercompany sales) rose 29.7% from HK$411.7 million in FY2024 to HK$533.8 million in FY2025. Profit for the year allocated to Southchina’s 49% non-controlling shareholders was HK$8.52 million in FY2024 and HK$9.15 million in FY2025 (total comprehensive income allocated to minorities was HK$8.84 million and HK$7.72 million after translation differences), implying consolidated net profit at Southchina of HK$17.4 million to HK$18.7 million per year. Because Alltronics holds 51% of Southchina, 49% of those earnings accrue to the minority partners, and HK$52.0 million of consolidated net assets (Note 1, page 108) represents minority equity at Southchina rather than capital attributable to Alltronics shareholders.
In the legacy PRC electronics lines outside Customer A, revenue contracted in 1H2026: walkie-talkie sales declined 65.1% year-over-year from HK$54.2 million to HK$18.9 million, and standalone electronic component sales fell 40.1% from HK$106.0 million to HK$63.5 million. Alltronics operates four manufacturing sites in mainland China (Shenzhen Allcomm, Shenzhen Southchina, Yichun, and Heyuan) with roughly 2,400 employees and HK$31.3 million in annual cash lease payments (FY2025 Annual Report, Note 14 and Note 29(b)). As legacy volumes declined, the group booked large orders from customers that exceeded the 10% revenue disclosure threshold for a single year before falling below it in the next period: Customer B generated HK$154.0 million in FY2024 (Note 4, page 122) and fell below 10% in FY2025; Customer C generated HK$143.0 million in FY2025 and fell below 10% in 1H2026.
Separately, in FY2025 trade receivable impairment charges (Note 19, page 151) rose from HK$0.75 million to HK$23.46 million. Gross receivables overdue by one to two years—corresponding to unpaid invoices originated in FY2024—increased to HK$25.43 million and were provisioned at a 100.0% loss rate, bringing total receivables overdue by more than one year to HK$52.53 million. The disclosures do not establish whether Customer B or Customer C account for the overdue receivables. However, we assign no value to opportunistic third-party EMS orders (previously valued at HK$45.0 million in July) because order repeatability and cash collection remain unproven. Our valuation for Legacy PRC Electronics relies on Yichun’s component operations (HK$110.0 million), Alltronics’s 51% share of Southchina’s third-party industrial molding business (HK$58.5 million), and the working-capital runoff of the walkie-talkie line (HK$15.0 million), totaling HK$183.5 million (HK$0.39 per share).
3. Overseas Subsidiaries and Non-Core Lending
In the fourth quarter of 2025, Alltronics committed HK$46.1 million in total consideration (HK$36.3 million in cash plus HK$9.8 million in deferred consideration) across three overseas acquisitions: 100% of Winner Sky in Malaysia (HK$9.15 million), 51% of EME Limited in the UK (HK$8.6 million cash plus HK$9.8 million deferred consideration for a heating-controls and thermostat manufacturer with FY2025 revenue of HK$194.1 million), and 51% of Momentum Innovation in Vietnam (HK$18.6 million).
In 1H2026, profit attributable to non-controlling interests shifted from positive HK$3.55 million in 1H2025 to negative HK$8.80 million. Assuming Southchina’s 49% minority share contributed positive HK$2.5 million to HK$3.5 million in the first half, the 49% minority share of EME and Momentum Vietnam absorbed an estimated loss of HK$11.3 million to HK$12.3 million, implying combined 100%-basis losses at EME and Momentum of roughly HK$23 million to HK$25 million in six months. On September 29, 2026, Alltronics also announced that Allpower Limited had filed a High Court writ claiming US$3.01 million (HK$23.48 million) in unpaid sales commissions related to Momentum Vietnam. Excluding potential 2027 Customer A production at Winner Sky (captured in Section 1), we revise the standalone value of the overseas subsidiaries from positive HK$64.0 million to negative HK$1.5 million.
Non-core investments and loans disclosed across Note 17 (financial assets at FVTPL), Note 20 (prepayments and other receivables), and Note 34 (related-party transactions) have absorbed approximately HK$79 million (net of repaid short-term bridge amounts) since 2020, with cumulative impairments and fair-value write-downs exceeding HK$33 million.
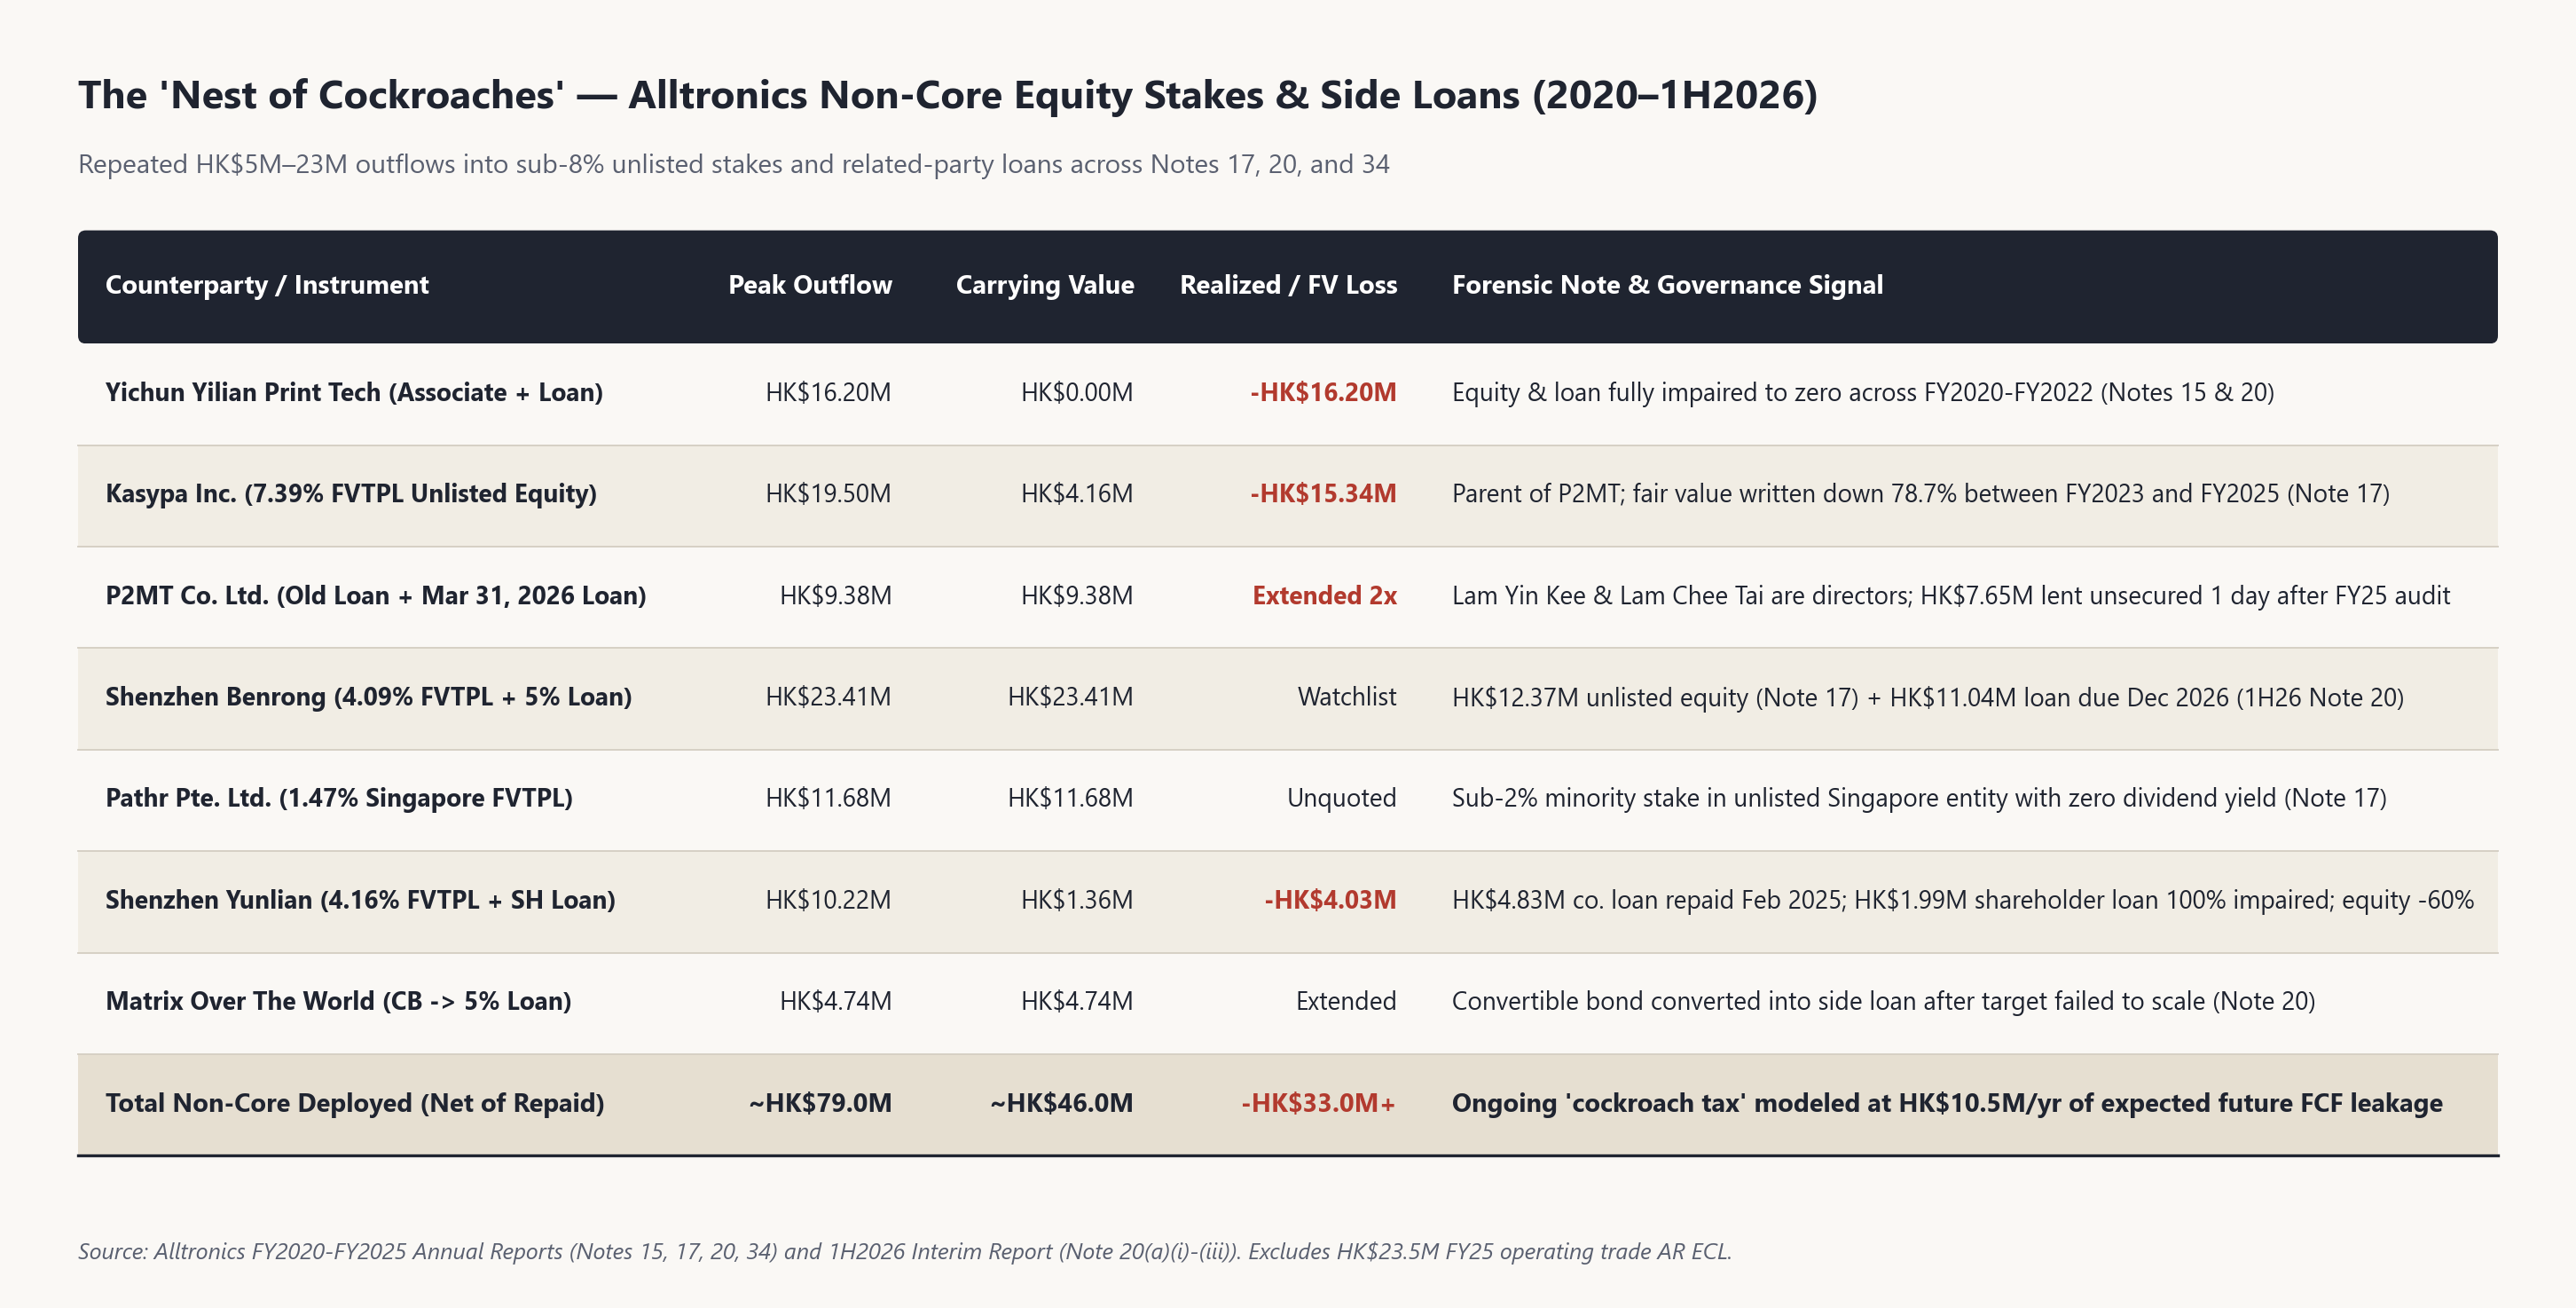
The most recent transaction appears in Note 20(a)(iii) of the 1H2026 interim report (page 29). Alltronics holds a 7.39% unlisted equity stake in Kasypa Inc., whose carrying value was written down by 78.7% from HK$19.50 million in FY2023 to HK$4.16 million at year-end 2025 (Note 17). Alltronics chairman Lam Yin Kee and executive director Lam Chee Tai serve as directors of Kasypa’s subsidiary P2MT Company Limited. An existing HK$1.73 million loan to P2MT had already been extended twice past its original 2024 maturity. On March 31, 2026, Alltronics entered into an agreement lending an additional HK$7.65 million unsecured at 5% interest to P2MT, maturing September 17, 2026.
4. Cash Attribution, Capitalized Overhead and Losses, and Entry Threshold
As of June 30, 2026, Alltronics reported HK$418.6 million in gross cash (HK$397.7 million in cash and equivalents plus HK$20.9 million in pledged bank deposits) and HK$176.5 million in bank borrowings (up from HK$157.7 million at year-end 2025), equating to HK$242.1 million of headline net cash against a market capitalization of HK$246.3 million (at HK$0.52 per share).
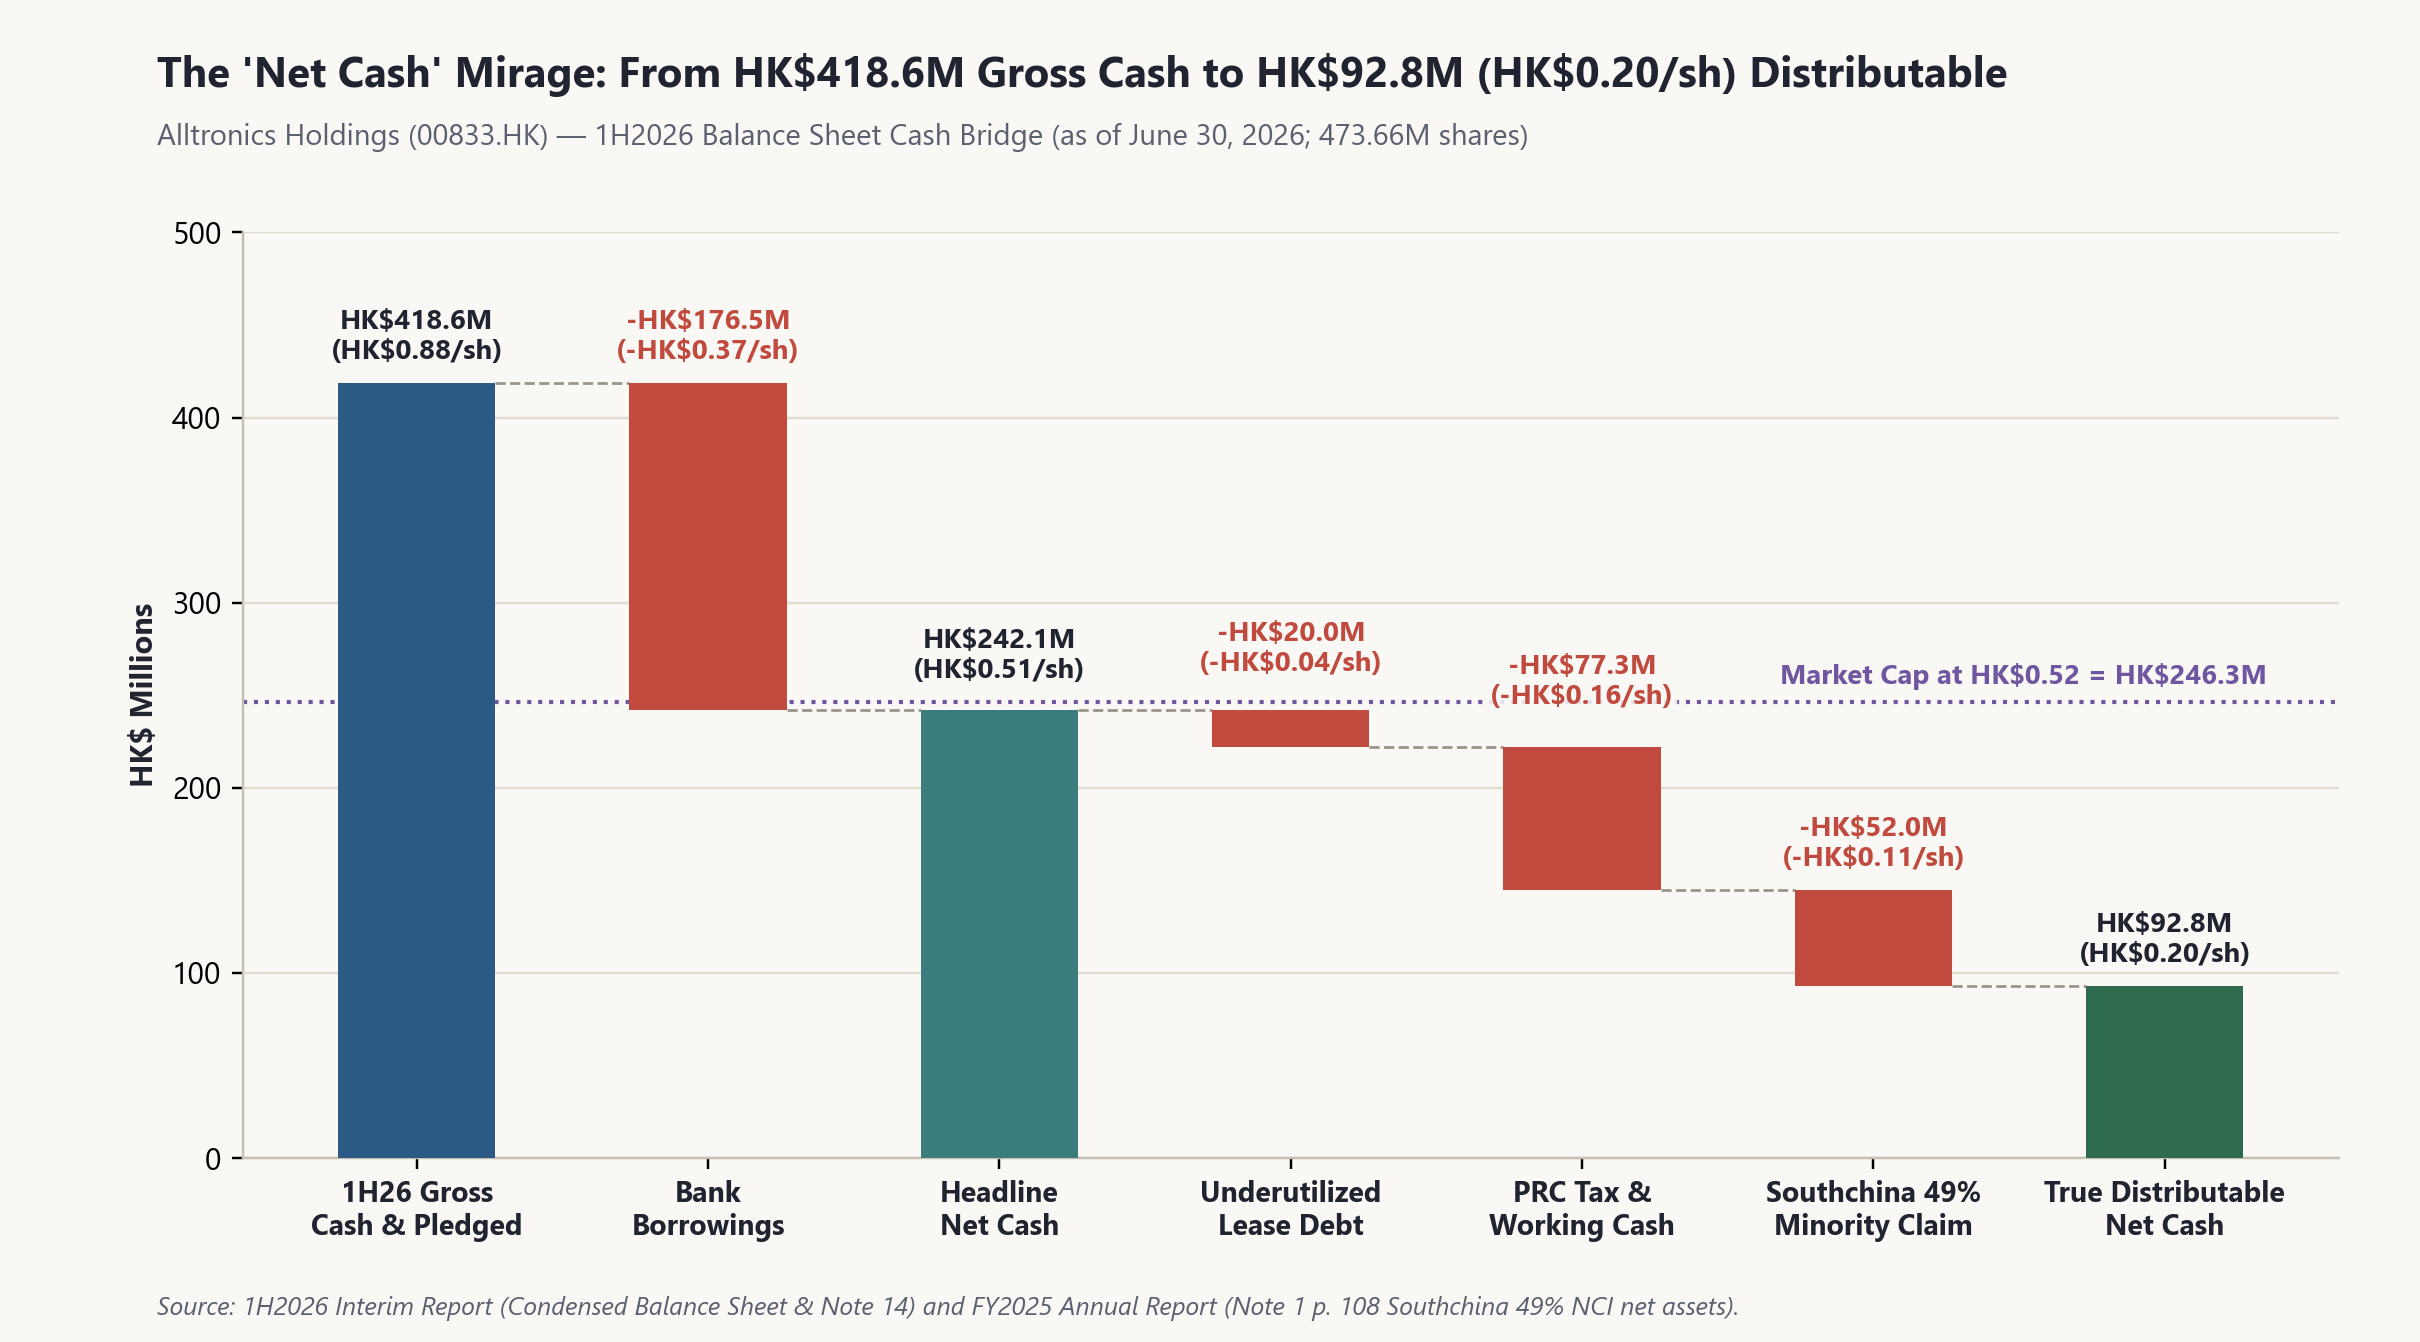
We make three adjustments to arrive at HK$92.8 million (HK$0.20 per share) of adjusted cash attributable to Alltronics shareholders:
Lease obligations on underutilized facilities (-HK$20.0 million): Out of HK$56.1 million in total lease liabilities, we deduct HK$20.0 million for excess factory lease commitments across legacy PRC and ramp-stage overseas sites.
PRC dividend withholding tax and minimum operating cash (-HK$77.3 million): Roughly HK$298 million of cash is held onshore in mainland RMB; we deduct HK$22.3 million for PRC dividend withholding tax (5% to 10%) and HK$55.0 million (~4.4% of annual revenue) for minimum working-capital cash required to run six manufacturing facilities.
Southchina 49% minority net assets (-HK$52.0 million): Because 51%-owned Southchina’s cash and working capital are 100% consolidated on Alltronics’s balance sheet while 49% of its accumulated net assets (HK$52.0 million per FY2025 Note 1, page 108) belong to the minority partners, we deduct the minority claim rather than treating 100% of consolidated subsidiary liquidity as attributable to parent shareholders.
We also deduct HK$180.0 million (-HK$0.38 per share), capitalized at a 10% discount rate, for corporate overhead and assumed annual investment and credit losses:
Unallocated Hong Kong headquarters overhead: HK$7.5 million per year (auditors’ remuneration of HK$2.7 million, listing and corporate secretarial fees, and parent-level administrative expenses net of HK$2.5 million bank interest income), capitalized at 10% = -HK$75.0 million.
Assumed annual investment and credit losses: Over the six years from 2020 through 1H2026, Alltronics incurred ~HK$33 million of non-core equity and loan write-offs (~HK$5.5 million per year) alongside two waves of trade receivable impairments (~HK$27 million in 2020–2023 and HK$23.5 million in FY2025). Because the controlling family holds 46.48% of the shares and has continued to approve non-core loans through March 2026, we treat this reinvestment drain as an ongoing feature of how retained cash flow is deployed and capitalize HK$10.5 million per year (~HK$5.5 million from non-core investments/loans and ~HK$5.0 million from non-core credit provisions, excluding historical write-offs already removed from carrying values) at 10% = -HK$105.0 million.
Combining the five components—Customer A at HK$245.0 million, Legacy PRC Electronics at HK$183.5 million, Overseas Subsidiaries at -HK$1.5 million, Capitalized Overhead & Losses at -HK$180.0 million, and Adjusted Cash at +HK$92.8 million—gives our fair value estimate of HK$339.8 million (HK$0.72 per share).
Our entry threshold is HK$0.36 per share, 50% below estimated fair value, reflecting trading illiquidity and capital-allocation risk. What we watch in the FY2026 annual report (due March/April 2027) is whether the HK$7.65 million P2MT loan (matured September 17, 2026) and the HK$11.04 million Shenzhen Benrong loan (maturing December 2026) are collected in cash without rollovers or new unlisted equity additions, and whether EME in the UK returns to profitability during the fourth-quarter heating season.